How to Apply for a Medicare Card: Step-by-Step 2024 Process
Navigating the process of applying for a Medicare card can feel like deciphering a bureaucratic maze—unless you know the precise path. Millions of Americans turn 65 each year, triggering automatic enrollment, yet many overlook critical deadlines or miss key documentation requirements. Even those eligible through disability or end-stage renal disease (ESRD) often stumble at the first hurdle: determining whether they qualify for Medicare Part A (hospital insurance) or must pay premiums for Part B (medical insurance). The stakes are high—delayed applications can mean gaps in coverage, and incorrect submissions may trigger unnecessary penalties. This guide cuts through the red tape, outlining every method to get your Medicare card, from the moment you verify eligibility to the day your card arrives.
The Medicare system, while robust, operates on strict timelines. For instance, if you’re not automatically enrolled at 65, you have just seven months to apply for a Medicare card without facing late-enrollment penalties. Disability recipients face a 21-month window post-approval, while ESRD patients must act within 90 days of treatment start. Missteps here—like assuming your employer plan covers everything or ignoring the Part D prescription drug deadline—can cost thousands in premiums. This isn’t just about paperwork; it’s about securing access to life-saving care. Whether you’re a retiree, a caregiver, or someone newly eligible due to a disability, understanding the nuances of how to apply for Medicare ensures you’re not left scrambling when the time comes.
The confusion often begins with the assumption that Medicare is a one-size-fits-all program. In reality, it’s a patchwork of parts (A, B, C, D) with overlapping rules. Part A is premium-free for most, but Part B requires monthly payments unless you qualify for extra help. Then there are Medicare Advantage plans (Part C) and prescription drug plans (Part D), each with their own enrollment periods. Add to this the maze of state-specific programs like Medicaid, and the process becomes a labyrinth. Yet, the system is designed to be navigable—if you approach it methodically. This guide will walk you through each step, from confirming your eligibility to submitting your application, and even troubleshooting common delays. By the end, you’ll know exactly how to get your Medicare card without missing a beat.
The Complete Overview of How to Apply for a Medicare Card
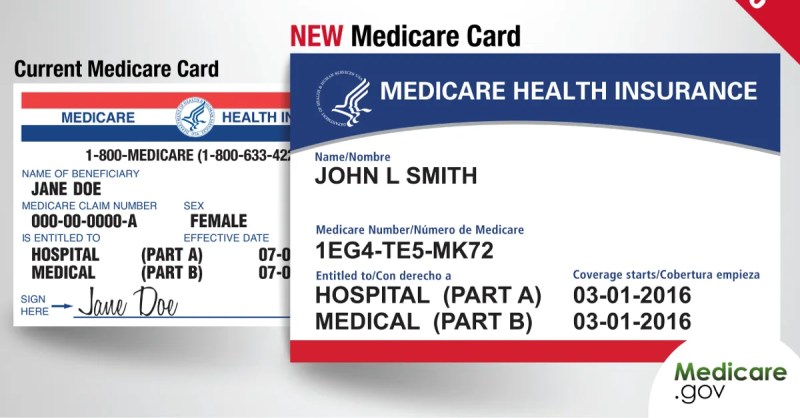
Applying for a Medicare card is not a single transaction but a series of coordinated actions, each with its own deadlines and documentation. The process begins with eligibility verification, which hinges on your work history (for Part A), citizenship status, and whether you’re receiving Social Security benefits. If you’re already collecting retirement or disability benefits, the government will enroll you automatically in Medicare Parts A and B. However, if you’re not receiving benefits, you’ll need to apply for Medicare proactively. The key here is timing: missing your initial enrollment period (IEP) can trigger penalties that last for life. For those eligible through disability, the 21-month window starts the month your disability benefits begin, while ESRD patients have a 90-day window from their first dialysis or transplant.
Once eligibility is confirmed, the next step is choosing how to apply for a Medicare card. You have three primary methods: online via the Social Security Administration’s (SSA) website, by phone, or in person at a local SSA office. Each method has its advantages—online is the fastest, phone offers real-time assistance, and in-person allows you to resolve issues immediately. After submission, processing typically takes 10–30 days, though delays can occur due to backlogs or missing documents. Your Medicare card will arrive by mail, and you’ll receive a welcome packet with crucial information about your coverage. It’s essential to activate your card promptly, as some providers require it before authorizing services. Failure to do so could leave you uninsured during a critical period.
Historical Background and Evolution
The Medicare program was signed into law in 1965 as part of President Lyndon B. Johnson’s Great Society initiatives, designed to provide healthcare coverage for Americans aged 65 and older. At the time, nearly half of seniors lacked health insurance, and the program was a revolutionary step toward universal healthcare access. Initially, Medicare consisted of two parts: Part A (hospital insurance) and Part B (medical insurance), funded by payroll taxes and monthly premiums, respectively. The program expanded in 1972 to include people under 65 with certain disabilities and those with end-stage renal disease (ESRD). Over the decades, Medicare has evolved to include additional options, such as Medicare Advantage (Part C) in 1997 and prescription drug coverage (Part D) in 2003, reflecting shifting healthcare needs and political priorities.
Table of Contents
- The Complete Overview of How to Apply for a Medicare Card
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: I’m turning 65 next month. Do I need to apply for a Medicare card if I’m already receiving Social Security benefits?
- Q: What documents do I need to apply for Medicare if I’m not receiving Social Security benefits?
- Q: Can I apply for a Medicare card online, and how long does it take?
- Q: What happens if I miss my Initial Enrollment Period (IEP) for Medicare?
- Q: Do I need to apply for a Medicare card separately if I’m enrolled in Medicaid?
- Q: What should I do if my Medicare card doesn’t arrive after 30 days?
- Q: Can I change my Medicare coverage after I’ve applied for a Medicare card ?
- Q: What’s the difference between Medicare and Medicaid, and do I need to apply for both ?
- Q: Is there a fee to apply for a Medicare card ?
- Q: How do I replace a lost or stolen Medicare card?
The application process for a Medicare card has also evolved alongside the program. In the early years, seniors had to visit local SSA offices or mail in paper applications, a cumbersome process that often led to delays. The advent of the internet in the 2000s streamlined enrollment, allowing applicants to apply for a Medicare card online and track their status in real time. Today, the SSA’s website is the preferred method for most applicants, offering 24/7 access and automated eligibility checks. Despite these advancements, the core principles remain: verifying eligibility, choosing coverage options, and submitting the application within the designated window. The system’s complexity has grown, but so too have the resources available to guide applicants through the process.
Core Mechanisms: How It Works
The mechanics of applying for Medicare revolve around three pillars: eligibility, enrollment periods, and coverage selection. Eligibility is determined by your work history (for Part A), age (65+), or disability status. If you’ve worked at least 10 years (40 quarters) in Medicare-covered employment, Part A is premium-free. Otherwise, you may need to pay a monthly premium. Part B, which covers doctor visits and outpatient care, requires a monthly premium unless you qualify for extra help through Medicaid or the Low Income Subsidy (LIS). The enrollment process is tied to specific periods: the Initial Enrollment Period (IEP), General Enrollment Period (January–March each year), and Special Enrollment Periods (SEPs) for those who qualify due to life changes like moving or losing employer coverage.
Once you’ve confirmed eligibility, the next step is selecting your coverage. If you’re automatically enrolled, you’ll receive your Medicare card and welcome packet in the mail. If not, you must apply for a Medicare card through your chosen method (online, phone, or in person) and specify whether you want Part B. You’ll also need to decide if you want to enroll in a Medicare Advantage plan (Part C) or a standalone Part D prescription drug plan. These choices can significantly impact your out-of-pocket costs and access to care. After submission, the SSA processes your application, issues your card, and sends you additional materials explaining your benefits. It’s critical to review these materials carefully, as they outline your rights, coverage limits, and how to file claims.
Key Benefits and Crucial Impact
Understanding the benefits of Medicare—and the potential consequences of inaction—is the first step toward making informed decisions about your healthcare. Medicare provides critical coverage for hospital stays, doctor visits, and prescription drugs, reducing financial strain during illness or injury. For many seniors, it’s the cornerstone of their healthcare strategy, offering peace of mind and access to specialized care. However, the program’s complexity means that even small oversights—like missing an enrollment deadline or failing to compare plans—can lead to costly gaps in coverage. The impact of Medicare extends beyond individual health; it’s a lifeline for millions, ensuring that age, disability, or illness doesn’t become a barrier to essential medical services.
The advantages of timely enrollment cannot be overstated. Enrolling during your Initial Enrollment Period avoids late penalties, which can add hundreds of dollars annually to your Part B premium. Additionally, delaying enrollment in Part D until you have creditable prescription drug coverage elsewhere can result in permanent premium increases. Medicare’s structure is designed to reward proactive applicants, but only if they navigate the system correctly. The key is to treat the application process as a strategic move—one that aligns your coverage with your healthcare needs and financial situation. Whether you’re transitioning from employer insurance or newly eligible due to disability, the right approach ensures you’re not left vulnerable during a critical life phase.
“Medicare isn’t just a program—it’s a safety net that millions rely on to stay healthy and financially secure. The difference between a seamless enrollment and a costly mistake often comes down to preparation and understanding the rules.”
— Medicare Rights Center
Major Advantages
- Premium-Free Part A for Most: If you’ve worked 10+ years in Medicare-covered employment, Part A has no monthly premium, covering hospital stays, hospice care, and some home health services.
- Flexible Enrollment Options: You can choose between Original Medicare (Parts A and B) or Medicare Advantage (Part C), which often includes prescription drug coverage and additional benefits like dental or vision.
- Prescription Drug Coverage (Part D): Standalone or bundled with Medicare Advantage plans, Part D helps manage the cost of medications, which can be prohibitively expensive without insurance.
- Protection Against Catastrophic Costs: Medicare’s out-of-pocket maximums (e.g., $8,000+ for inpatient hospital services in 2024) prevent financial ruin from unexpected medical expenses.
- Access to Specialized Care: Medicare covers a wide range of services, including dialysis, chemotherapy, and skilled nursing facility stays, ensuring continuity of care regardless of age or disability status.

Comparative Analysis
| Aspect | Original Medicare (Parts A & B) | Medicare Advantage (Part C) |
|---|---|---|
| Coverage Scope | Covers hospital (Part A) and medical (Part B) services nationwide; requires separate Part D for prescriptions. | Bundles Parts A, B, and often D; may include extra benefits like dental, vision, or gym memberships. |
| Cost Structure | Part A: $0 premium (if eligible); Part B: $174.70/month (2024); out-of-pocket costs (deductibles, coinsurance). | Monthly premium varies by plan (often lower than Part B + Part D combined); may have copays for services. |
| Network Restrictions | No network; accepts any provider who participates in Medicare. | Uses provider networks; out-of-network care may not be covered or fully reimbursed. |
| Enrollment Flexibility | Enroll during IEP or General Enrollment; can switch between Parts A/B and supplemental plans annually. | Enrolls during IEP or Annual Election Period (Oct 15–Dec 7); plan options vary by county. |
Future Trends and Innovations
The Medicare program is poised for significant changes in the coming years, driven by demographic shifts, technological advancements, and policy reforms. As the baby boomer generation ages, demand for healthcare services will surge, placing pressure on the system to innovate. One major trend is the expansion of telehealth services, which gained traction during the COVID-19 pandemic and are now being integrated into Medicare’s long-term structure. This shift allows beneficiaries to access care remotely, reducing barriers for those in rural areas or with mobility challenges. Additionally, value-based care models—where providers are reimbursed based on patient outcomes rather than volume—are becoming more prevalent, aiming to improve quality while controlling costs.
Another key innovation is the growing role of artificial intelligence in Medicare administration. AI is being used to streamline eligibility determinations, detect fraud, and personalize beneficiary communications. For example, chatbots and virtual assistants can guide applicants through the process of applying for a Medicare card, answering questions in real time and reducing wait times. Moreover, the push toward interoperability—where electronic health records (EHRs) seamlessly share data across providers—will enhance coordination of care, ensuring beneficiaries receive consistent treatment. As these trends unfold, the Medicare application process may become even more user-friendly, with automated tools handling routine tasks and human advisors focusing on complex cases.

Conclusion
Applying for a Medicare card is a critical milestone for millions of Americans, marking the transition to a new phase of life and healthcare management. The process may seem daunting, but breaking it down into manageable steps—verifying eligibility, choosing coverage, and submitting your application—makes it achievable. The key is to act within your enrollment window, gather the necessary documents, and leverage available resources, whether through the SSA’s website, local offices, or third-party assistance programs. By doing so, you ensure uninterrupted access to the care you’ve earned and paid for over decades.
Medicare is more than a government program; it’s a lifeline that protects against financial ruin and ensures dignity in aging. The decisions you make during enrollment—whether to opt for Original Medicare or a Medicare Advantage plan, or how to manage prescription costs—will shape your healthcare experience for years to come. Stay informed, ask questions, and don’t hesitate to seek help if needed. The goal isn’t just to get your Medicare card; it’s to secure a foundation for health and well-being in your golden years.
Comprehensive FAQs
Q: I’m turning 65 next month. Do I need to apply for a Medicare card if I’m already receiving Social Security benefits?
A: No, you’ll be automatically enrolled in Medicare Parts A and B starting the first day of the month you turn 65. You’ll receive your Medicare card in the mail about three weeks before your coverage begins. However, you should review your welcome packet to confirm your coverage details and decide if you want to enroll in a Medicare Advantage or Part D plan.
Q: What documents do I need to apply for Medicare if I’m not receiving Social Security benefits?
A: You’ll need your Social Security number, proof of citizenship or lawful residency (e.g., U.S. birth certificate or green card), and proof of age (e.g., driver’s license or passport). If you’re applying based on disability, bring your Social Security award letter. For online applications, digital copies of these documents are sufficient.
Q: Can I apply for a Medicare card online, and how long does it take?
A: Yes, you can apply online via the SSA’s website. Processing typically takes 10–30 days, after which your card will be mailed to your address on file. If you need your card sooner, you can call the SSA at 1-800-772-1213 or visit a local office. Note that some states offer expedited processing for certain applicants.
Q: What happens if I miss my Initial Enrollment Period (IEP) for Medicare?
A: If you miss your IEP, you’ll face late-enrollment penalties. For Part B, the penalty is 10% of the standard premium for each 12-month period you were eligible but didn’t enroll. For Part D, the penalty is calculated based on the average national premium and the number of months you went without creditable coverage. You can still enroll during the General Enrollment Period (January–March), but your coverage will start July 1.
Q: Do I need to apply for a Medicare card separately if I’m enrolled in Medicaid?
A: If you qualify for both Medicare and Medicaid, you may be automatically enrolled in certain benefits, such as extra help with Part D costs or Medicare premiums. However, you should still verify your eligibility and ensure all necessary paperwork is submitted to avoid gaps in coverage. Medicaid programs vary by state, so check with your local Medicaid office for specific requirements.
Q: What should I do if my Medicare card doesn’t arrive after 30 days?
A: If your card is delayed, contact the SSA at 1-800-MEDICARE (1-800-633-4227) or TTY 1-877-486-2048. Provide your Social Security number and date of birth to check your application status. In some cases, you may need to submit additional documentation or visit a local office to resolve the issue. Most beneficiaries receive their cards within 10–14 days, but processing times can vary.
Q: Can I change my Medicare coverage after I’ve applied for a Medicare card?
A: Yes, you can switch between Original Medicare and Medicare Advantage during the Annual Election Period (October 15–December 7) or if you qualify for a Special Enrollment Period (e.g., due to moving or losing employer coverage). For Part D prescription plans, you can change during the Annual Election Period or if you experience significant life changes. Always review your options annually to ensure your plan still meets your needs.
Q: What’s the difference between Medicare and Medicaid, and do I need to apply for both?
A: Medicare is a federal program for people 65+ or with certain disabilities, while Medicaid is a joint federal-state program for low-income individuals and families. You may qualify for both if your income and assets fall below Medicaid’s limits. Medicaid can help cover Medicare premiums, deductibles, and out-of-pocket costs. You’ll need to apply separately for each program, often through your state’s Medicaid agency.
Q: Is there a fee to apply for a Medicare card?
A: No, applying for a Medicare card is free. However, there may be premiums for certain parts of Medicare (e.g., Part B or Part D) depending on your income and eligibility. The SSA and Medicare do not charge fees for processing applications, so be wary of third-party websites or organizations that claim to expedite your application for a cost.
Q: How do I replace a lost or stolen Medicare card?
A: To replace your card, call 1-800-MEDICARE (1-800-633-4227) or visit the SSA’s website. You’ll need to verify your identity and provide your Social Security number. A new card will be mailed to you within 10–14 days. While you wait, keep your Medicare number secure, as it’s needed to access care. Avoid carrying your card with you unless necessary, as it contains sensitive information.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Gouv.