How to Accurately Calculate Cost of Goods Sold for Smarter Business Decisions
Every business transaction begins with a fundamental question: What does it truly cost to produce or acquire the products you sell? The answer lies in calculating cost of goods sold (COGS), a metric that separates the wheat from the chaff in financial reporting. Without precise COGS calculations, profit margins become guesswork, tax obligations blur, and strategic decisions lack a solid foundation. The stakes are higher than most realize—misreporting COGS by even a few percentage points can distort financial health, trigger audits, or mislead investors.
Yet, despite its critical role, COGS remains one of the most misunderstood financial concepts. Many entrepreneurs and accountants treat it as a static line item in ledgers, unaware of how inventory valuation methods, supply chain fluctuations, or even seasonal demand can drastically alter its impact. The reality is that COGS is dynamic—a living metric that evolves with operations, technology, and market conditions. Mastering its calculation isn’t just about compliance; it’s about unlocking a direct line to operational efficiency and profitability.
Consider this: A retail chain might assume COGS is simply the purchase price of inventory, but when they fail to account for shipping costs, import duties, or the depreciation of warehouse equipment, their reported profits become inflated. Meanwhile, a manufacturer using outdated FIFO (First-In, First-Out) methods might overstate earnings during inflationary periods. The difference between these approaches isn’t theoretical—it’s millions in lost revenue, misallocated budgets, or even failed expansions. The precision of COGS calculation determines whether a business thrives or stumbles in the red.

The Complete Overview of Calculating Cost of Goods Sold
Calculating cost of goods sold isn’t a one-size-fits-all process; it’s a tailored equation that adapts to industry, scale, and business model. At its core, COGS represents the direct costs attributable to producing or procuring the goods a company sells during a specific period. This includes raw materials, labor directly tied to production, manufacturing overhead (like factory utilities), and any other expenses that transform inputs into finished products. What’s excluded? Indirect costs such as marketing, administrative salaries, or R&D—these fall under operating expenses, not COGS.
The challenge lies in the how. For a coffee shop, COGS might be straightforward: the cost of beans, milk, and disposable cups. But for a tech hardware manufacturer, it involves complex supply chain logistics, component sourcing, and even the amortization of intellectual property. The method of calculation—whether periodic (end-of-period inventory valuation) or perpetual (real-time tracking)—also dictates accuracy. Small businesses might rely on manual spreadsheets, while enterprises deploy ERP systems with automated COGS modules. The choice of inventory valuation method (FIFO, LIFO, or weighted average) further complicates the picture, especially in volatile markets.
Historical Background and Evolution
The concept of COGS traces back to the Industrial Revolution, when mass production demanded systematic cost tracking. Early accountants in the 19th century developed the idea of separating "cost of sales" from other expenses to provide clearer financial snapshots for investors. The Uniform Cost Accounting Act of 1919 in the U.S. formalized requirements for public companies, but it wasn’t until the 1930s that GAAP (Generally Accepted Accounting Principles) codified COGS as a distinct line item. This evolution reflected a shift from agrarian economies, where inventory was perishable and seasonal, to industrial ones where scalability required precision.
Table of Contents
- The Complete Overview of Calculating Cost of Goods Sold
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: What’s the difference between COGS and operating expenses?
- Q: Can small businesses use LIFO for tax purposes?
- Q: How does seasonal demand affect COGS calculations?
- Q: What happens if COGS is miscalculated in an audit?
- Q: How does dropshipping change COGS calculation?
- Q: Can COGS include digital products or services?
- Q: What’s the impact of inflation on COGS?
Today, COGS is governed by international standards like IFRS (International Financial Reporting Standards) and U.S. GAAP, which mandate consistency and transparency. The rise of e-commerce and global supply chains has further refined its calculation, introducing variables like cross-border tariffs, digital inventory (e.g., SaaS licenses), and just-in-time manufacturing. Historically, COGS was a reactive measure—used primarily for tax filings. Now, it’s a proactive tool, integrated into dynamic pricing, inventory optimization, and even AI-driven demand forecasting. The metric has grown from a compliance checkbox to a competitive differentiator.
Core Mechanisms: How It Works
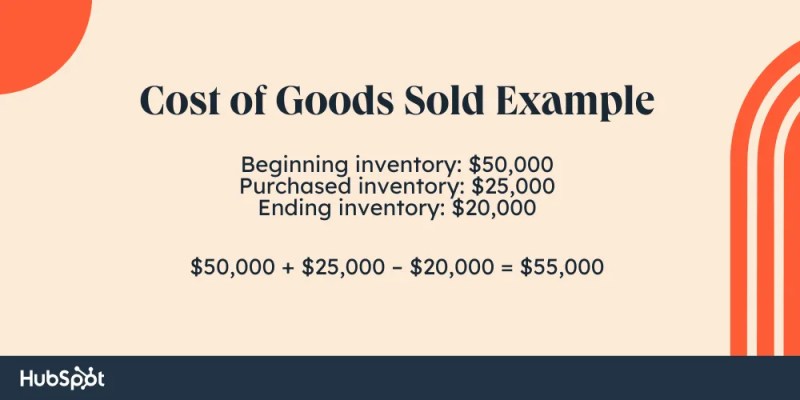
The calculation of COGS hinges on two primary approaches: periodic and perpetual inventory systems. The periodic method, simpler but less accurate, involves taking a physical inventory count at the end of an accounting period and applying it to the formula:
COGS = Beginning Inventory + Purchases – Ending InventoryThis method works for businesses with low transaction volumes (e.g., seasonal retailers), but it’s vulnerable to shrinkage, theft, or human error. The perpetual system, favored by high-volume operations, tracks inventory in real time using barcodes, RFID, or ERP software, updating COGS with each sale. The formula remains the same, but the data is granular and immediate.
Beyond the inventory method, the choice of cost flow assumption—FIFO, LIFO, or weighted average—drastically alters COGS. FIFO assumes the oldest inventory is sold first, which aligns with physical flow but can overstate COGS during inflation. LIFO does the opposite, matching recent costs to revenue, which reduces taxable income but may not reflect actual sales patterns. Weighted average smooths fluctuations by averaging all inventory costs, offering a middle ground. The IRS and GAAP allow LIFO only for tax purposes in the U.S., adding another layer of strategic complexity. For businesses in high-inflation industries (e.g., commodities), LIFO can be a tax-saving powerhouse, while FIFO might be preferable for consistency in stable markets.
Key Benefits and Crucial Impact
Accurately calculating cost of goods sold isn’t just an accounting exercise—it’s the backbone of financial health. A precise COGS figure directly impacts profit margins, tax liabilities, and investor confidence. For example, a restaurant chain that underreports COGS might appear more profitable than it is, leading to overconfident expansion plans. Conversely, overstating COGS could trigger unnecessary cost-cutting measures. The ripple effects extend to pricing strategies: if COGS is miscalculated, competitors with tighter controls could undercut prices, eroding market share. Beyond internal operations, COGS influences external perceptions—lenders scrutinize it when evaluating loan applications, and public companies must disclose it in filings like the 10-K.
The strategic advantage lies in using COGS as a diagnostic tool. By comparing COGS to revenue, businesses can identify inefficiencies—such as supplier price hikes, wasteful production processes, or excess inventory. A sudden spike in COGS might signal supply chain disruptions, while a persistent decline could indicate quality compromises. In industries like pharmaceuticals or aerospace, where compliance and traceability are critical, COGS calculations must account for regulatory costs (e.g., FDA inspections), adding another dimension to financial reporting. The metric doesn’t just reflect the past; it predicts the future.
"COGS is the financial equivalent of a stethoscope for a business. It doesn’t just measure heartbeat—it reveals the underlying health of the entire organism." — Michael C. Thomsett, CPA and Author of Accounting for Dummies
Major Advantages
- Profitability Clarity: COGS strips away operational noise, revealing true gross profit. Without it, net income becomes a misleading figure.
- Tax Optimization: Strategic use of LIFO (where permitted) can legally reduce taxable income during inflationary periods.
- Investor Trust: Accurate COGS reporting builds credibility, as it aligns with GAAP/IFRS standards and reduces audit risks.
- Operational Insights: Trends in COGS highlight inefficiencies—e.g., rising material costs or labor shortages—before they become crises.
- Pricing Strategy: Understanding COGS enables data-driven pricing; businesses can adjust markups to maintain margins despite cost fluctuations.
Comparative Analysis
| Aspect | Periodic Inventory System | Perpetual Inventory System |
|---|---|---|
| Accuracy | Lower (depends on end-of-period counts) | Higher (real-time tracking) |
| Complexity | Simple, manual-friendly | Requires automation (ERP, POS systems) |
| Best For | Small businesses, low-volume sales | E-commerce, manufacturing, high-turnover industries |
| Cost Flow Assumptions | Any (FIFO, LIFO, average) | Any, but perpetual systems often integrate FIFO/LIFO automatically |
Future Trends and Innovations
The future of calculating cost of goods sold is being reshaped by technology and globalization. AI and machine learning are already automating inventory valuation, predicting COGS fluctuations based on supplier data, and even optimizing reorder points to minimize holding costs. Blockchain is emerging as a game-changer for supply chain transparency, allowing businesses to trace the entire lifecycle of raw materials—from mine to shelf—ensuring COGS includes only verified, ethical costs. For example, a coffee brand using blockchain could calculate COGS by tracking fair-trade premiums paid to farmers, reducing reputational risks while maintaining accuracy.
Another trend is the convergence of COGS with sustainability metrics. Investors and consumers increasingly demand "true cost accounting," which factors in environmental and social costs (e.g., carbon footprints, labor conditions) into COGS calculations. Regulations like the EU’s Corporate Sustainability Reporting Directive (CSRD) are pushing companies to disclose these extended COGS components. Meanwhile, the rise of "circular economy" models—where COGS includes the cost of recycling or refurbishing products—is redefining the metric for industries like electronics and fashion. As ESG (Environmental, Social, and Governance) criteria dominate financial analysis, COGS will evolve from a purely financial figure to a holistic business performance indicator.

Conclusion
Calculating cost of goods sold is more than a routine accounting task—it’s a strategic imperative that intersects with finance, operations, and even corporate responsibility. The precision of COGS determines whether a business survives lean quarters, attracts investors, or pivots effectively in disruptive markets. Yet, the process is far from static. As supply chains globalize, technologies advance, and regulatory expectations evolve, the methods for calculating COGS must adapt. The businesses that thrive will be those that treat COGS not as a line item, but as a dynamic tool for decision-making.
For entrepreneurs, the message is clear: invest in the right systems—whether it’s ERP software, AI-driven analytics, or blockchain-ledger tracking—to ensure COGS calculations are not just accurate, but actionable. For accountants, the challenge is to move beyond compliance and use COGS as a lens to uncover operational truths. And for investors, understanding COGS is the first step in separating hype from substance in financial statements. The cost of goods sold isn’t just a number—it’s the foundation upon which sustainable growth is built.
Comprehensive FAQs
Q: What’s the difference between COGS and operating expenses?
A: COGS includes only direct costs tied to producing or procuring goods sold (e.g., raw materials, direct labor). Operating expenses (OPEX) cover indirect costs like rent, marketing, or administrative salaries. The key distinction is whether the expense is directly tied to revenue generation. For example, a factory manager’s salary might be COGS if they oversee production, but an HR manager’s salary is OPEX.
Q: Can small businesses use LIFO for tax purposes?
A: Yes, but only in the U.S. under IRS rules. Small businesses can adopt LIFO for tax filings even if they use FIFO or average cost for financial reporting (a practice called "LIFO conformity"). However, switching to LIFO requires IRS approval and a detailed justification. For non-U.S. businesses, LIFO is rarely permitted under IFRS, which mandates FIFO or weighted average.
Q: How does seasonal demand affect COGS calculations?
A: Seasonal demand distorts COGS in two ways: (1) Inventory Valuation: If a business buys inventory in bulk before peak seasons (e.g., holiday toys), ending inventory counts may be artificially high, understating COGS. (2) Cost Fluctuations: Suppliers often raise prices before peak demand, inflating COGS in later periods. To mitigate this, businesses use perpetual inventory systems or adjust for seasonality in financial forecasts.
Q: What happens if COGS is miscalculated in an audit?
A: Miscalculated COGS can trigger adjustments, penalties, or even fraud investigations. Auditors cross-check COGS with purchase orders, production records, and inventory counts. Common red flags include inconsistent valuation methods, lack of documentation for write-offs, or discrepancies between physical inventory and book records. In severe cases, businesses may face back taxes, interest charges, or reputational damage if the error suggests intentional misreporting.
Q: How does dropshipping change COGS calculation?
A: Dropshipping simplifies COGS because the business doesn’t hold inventory. Instead, COGS is the wholesale price paid to the supplier at the time of sale, plus any shipping or handling fees. However, challenges arise with supplier price volatility (e.g., sudden markup increases) or hidden costs (e.g., restocking fees). Dropshippers must track supplier invoices meticulously and account for currency fluctuations if sourcing internationally.
Q: Can COGS include digital products or services?
A: Traditionally, COGS applies to tangible goods, but digital products (e.g., software licenses, e-books) and services (e.g., consulting hours) are treated differently. For digital products, COGS might include development costs amortized over sales, while services typically exclude direct costs (since labor is OPEX). GAAP allows capitalizing certain digital costs (e.g., SaaS development) as inventory if they’re resold, but this requires careful documentation.
Q: What’s the impact of inflation on COGS?
A: Inflation increases COGS because raw material and labor costs rise over time. Under FIFO, older (cheaper) inventory is sold first, so COGS grows gradually. Under LIFO, recent (higher) costs are matched to revenue, leading to higher COGS and lower taxable income—a key reason many businesses adopt LIFO during inflation. Without adjustments, inflation can erode profit margins, necessitating price hikes or cost-cutting measures.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Gouv.